Insurance rates won’t go up in wake of 2026 wildfires
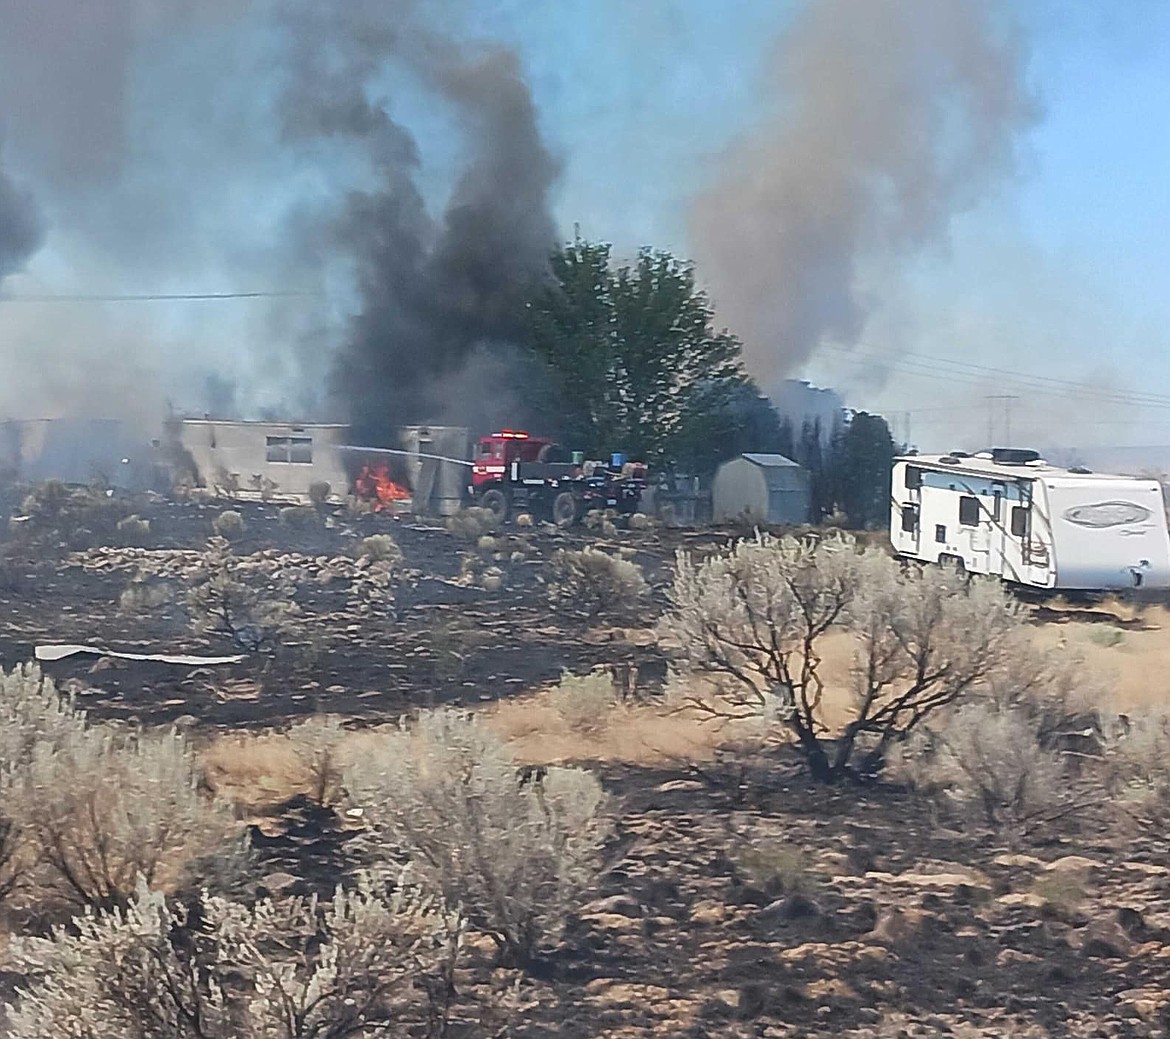
Grant County Fire District 13 firefighters extinguish a wildfire in 2023. Despite the increase in wildfires in recent years, Moses Lake insurance agent Chris Arnberg said homeowners shouldn’t worry about insurance premiums skyrocketing.
FILE PHOTO
MOSES LAKE — Almost three-fifths of American homeowners have concerns about their insurance rates going up due to wildfires, according to a study by the insurance website LendingTree.com. But Moses Lake insurance agent Chris Arnberg said we don’t have much to worry about in the Columbia Basin.
“I don't think we’ll see rates going up,” said Arnberg, who represents American Family Insurance. “If you're purchasing a home that's nowhere near any kind of potential wildfire, then your rates shouldn't go up more than inflation.”
Any way you measure it, wildfires have gotten worse in Washington in recent years. In 2024, our state ranked 10th in the nation for the amount of acreage burned and 11th for the number of wildfires and had the 20th-greatest increase in fires between 2019 and 2024, according to data from the National Interagency Fire Service compiled by LendingTree.com. For much of this summer, all we had to do was step outside and inhale to be reminded that areas to the north and east of the Columbia Basin were on fire.
Still, the Columbia Basin, for the most part, isn’t considered a risky area by insurance companies, Arnberg said.
“The only time it becomes a concern for (American Family Insurance) is if you have a lot of sagebrush or an area that's completely undeveloped, and your home's very close to it, and there's no like barrier between you and that,” Arnberg said. “It's still a pretty low wildfire score compared to, say, Cle Elum or somewhere like that.”
Part of that stems from changes in the way insurance companies assess what is or isn’t a risky area, Arnberg explained. In the past, companies determined the danger, and hence the premium, based on the home’s ZIP code. That means a customer living on the shore of Moses Lake would pay the same premium as one living in the sagebrush between Moses Lake and Wilson Creek, both in the 98837 ZIP code but very different terrain and hence different risk levels.
Today’s insurance carriers can use satellite data for more precise assessment, Arnberg said.
“There are companies that (figure) the data, and they get it to within 100 feet,” he said. “Each home is going to be unique because it’s all based on how close it is to a potential wildfire. I don’t see rates going up because we’ve been able to be much more precise about what the risk is from one area to the next.”
A few insurance companies do still assess by ZIP code, Arnberg said; he knows of one carrier that refuses to cover any homes in the Wenatchee ZIP code because of fire risk.
People living in forested areas outside Grand and Adams counties may find themselves facing more difficulty getting insured, Arnberg said. There are carriers that specialize in those higher-risk areas, he said.
“Sometimes they don't even do a traditional insurance (policy) where they're pooling the money of the policyholders to pay out the claims. They go out and find investors who are willing to put their money on the line in order to insure a home. It's going to cost more, but they will put their money on the line. And if somebody does lose their home, the money will be there to rebuild it.”
Originally, homeowners’ insurance was specifically created to insure against fire, but over the decades more and more potential dangers have been added to a comprehensive plan, Arnberg said. So while fire may be a worry, it’s not what homeowners should be most concerned about.
“Probably the biggest cause of loss in Washington state is actually plumbing leaks,” he said. “And then theft (is) a very important one because if somebody if somebody breaks in and burglarizes your home, then it's pretty expensive to replace all the valuables … In 16 years at this agency, we've had maybe one very serious fire and just a few minor, kitchen fire-type situations, but every week it seems like we have a plumbing leak. That costs a lot of money to dry out, and if you have to replace the drywall and insulation and flooring, it can get pretty expensive.”